
Big college news can hit two different ways at once.
Relief, because maybe the cost will not be as impossible as it seems. And anxiety, because it raises the same old question: Are we doing enough to prepare our kids for what comes next?
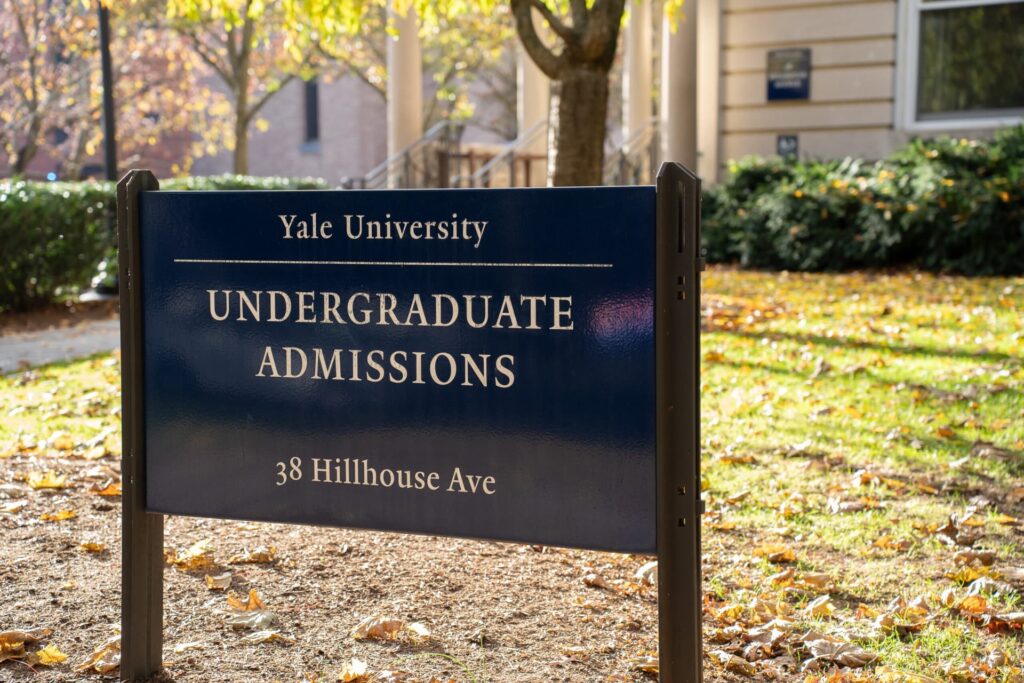
This week, Yale announced a major change to its financial aid: tuition will be waived for newly admitted undergraduates from families with incomes under $200,000, and Yale will waive tuition and other costs for families under $100,000 (for the class enrolling this fall).
Let’s break down what that actually means, what it does not mean, and how to think about college planning in a calmer, more realistic way.
The Headline, In Plain Language
Yale’s announcement has two big thresholds:
- Under $100,000 household income: Yale says it will waive tuition and also waive other costs (which can include things like housing and meals).
- Under $200,000 household income: Yale says it will waive tuition.
That matters because the “full price” cost to attend Yale is now more than $90,000 per year, according to the article.
It also matters because Yale is not alone. The article notes similar, increasingly generous financial aid moves from other elite schools, including Harvard, Penn, and M.I.T.
Definition Moment: What “Free Tuition” Actually Means
When we talk about free tuition, we don’t mean college is fully free for everyone. We mean one major line item (tuition) may be covered, while other costs may still exist depending on your family’s situation and the school’s policy.
This distinction matters because “tuition” is only one part of the total cost of attendance. Families still need to understand the difference between:
- Tuition
- Housing and meals
- Books and supplies
- Travel to and from campus
- Health insurance and fees
In Yale’s case, the article notes that for the lowest-income students, aid packages at Yale and peer schools can include housing and meals, travel allowances, medical insurance, and start-up grants for books and supplies.
Why Schools Are Expanding Aid Right Now
There are a few forces converging here, and the article names them directly.
One is the Supreme Court’s 2023 decision limiting what universities may do to recruit racially diverse student bodies. The article notes that schools are stepping up financial aid in part because income and race are often correlated, and expanding aid is a legal way to keep attracting diverse applicants.
Another is broader skepticism about higher education. The article points to declining public trust in higher education, which creates pressure on universities to prove value and accessibility.
And there is also a competitive reality: selective schools are competing for talented students, and affordability is one of the biggest deciding factors for many families.
If Your Family Might Qualify, Here’s What To Do (Calmly)
If your household income is in the range these policies reference, the most important thing to understand is this:
You do not have to guess. You can plan your next step around information, not vibes.
A practical approach:
- Treat headlines as a starting point, not a guarantee.
Policies often have details: assets, family size, multiple kids in college, and how “income” is calculated can all matter. - Look for the school’s net price calculator.
Most colleges provide a tool that estimates cost after aid. It is not perfect, but it is usually more grounded than internet speculation. - Build a “paperwork habit” early.
Financial aid is often as much about process as it is about need. Getting comfortable with forms and timelines is an advantage. - Keep savings goals flexible.
Even if tuition might be covered, other costs exist. Having some savings can still reduce stress and reduce student borrowing.
One detail from the article that’s easy to miss: Yale said that students from 80 percent of U.S. households would qualify for free tuition, and students from almost half would be eligible for an entirely free Yale education.
If that’s accurate for your family, it’s meaningful. It’s also not a reason to stop planning. It’s a reason to plan with less fear.
If Your Family Probably Won’t Qualify, This Still Matters
Even if your income is above the thresholds in this Yale free tuition announcement, this news still gives you something useful:
A reminder that “sticker price” is not the same as what many families pay.
It also highlights a bigger truth about college planning:
- You can be a strong saver and still benefit from aid.
- You can save less than you hoped and still find a workable path.
- You can plan without making your child feel like college is a financial crisis they have to solve.
If you’re in the “we might qualify, but I’m not sure” zone, that’s normal. The best move is not to spiral. It’s to create a simple system so you can learn what’s real as your child gets closer to college age.
A Simple College Planning Checklist That Doesn’t Create Panic
Here’s a calm checklist you can revisit once a year.
1) Know Your Three Buckets
Think in three buckets, not one giant number:
- What you can pay from current income
- What you can save over time
- What might be covered by financial aid or scholarships
This helps you avoid the all-or-nothing feeling that makes parents freeze.
2) Save For Options, Not For Perfection
If you can save, save. If you can only save a little, save a little. The goal is not to fully fund an unknown future. The goal is to reduce pressure and create flexibility.
This is where our “time matters more than timing” philosophy shows up in real life. Small, consistent steps usually beat intense bursts that burn out.
3) Keep A Running List of “Future Questions”
When college comes up, you do not need answers immediately. You need a place to capture questions, like:
- What would we consider “affordable” per year?
- Would we prefer a school closer to home?
- How do we feel about student loans, in general?
- What kind of support would our child need to thrive?
Over time, those questions become clarity.
4) Don’t Put the Pressure on Your Kid
This is the emotional core.
A child does not need to feel responsible for adult-scale financial decisions. What they do benefit from is hearing calm, honest language like:
- “College can be expensive, but there are many ways families pay for it.”
- “Our job is to plan. Your job is to learn and explore what you like.”
- “We’ll make decisions together when the time comes.”
Money confidence grows when kids feel safe asking questions, not when they feel like the stakes are on their shoulders.
What This News Can Teach Kids (Even If They Never Apply to Yale)
You can use this moment to teach one of the healthiest money lessons there is:
Big goals are often funded through systems, not heroics.
Financial aid, savings, scholarships, work study, community college pathways, in-state tuition, family support. These are all systems.
If your child is old enough to notice college conversations, you can keep it simple:
- “Some schools help families a lot with cost.”
- “Planning early gives us more choices later.”
- “You don’t have to figure it out alone.”
That’s a money lesson and a life lesson.
Closing
Yale’s announcement is a meaningful shift: it reduces tuition costs for many families and signals a broader push among elite schools to expand financial aid.
If you only do one thing this week, start a one-page “college plan” note: three buckets (pay, save, aid) plus a short list of questions to revisit each year.
Save this and share with a friend or family member. Comment with your questions.