
If “financial literacy for kids” sounds like a school unit you missed, you are not alone.
A lot of parents want to help their kids feel confident with money. They just do not want to turn family life into a lecture. We feel the same way.
Here is our calm definition, plus what to focus on first.
A Quick Definition Moment
When we talk about financial literacy for kids, we do not mean memorizing terms or mastering spreadsheets. We mean building comfort, language, and simple habits kids can repeat in real life.
The Three Parts That Matter Most
Financial literacy gets easier when we stop treating it like a subject and start treating it like a skill your child grows into.
In our experience, the most useful version has three parts.
1) Comfort
Comfort means money does not feel scary, taboo, or tense.
It looks like:
- Your child feels safe asking questions.
- You can say “we cannot buy that today” without shame or panic.
- Money talk does not become a big emotional moment every time.
Comfort comes first because kids learn fast when they feel safe.
2) Language
Language means your child has simple words to describe what is happening.
Not fancy words. Just words that help them think clearly:
- save
- spend
- plan
- choose
- wait
- give
- earn
- own
When kids have language, they can tell you what they want, what they worry about, and what they notice. That is where real learning starts.
3) Habits
Habits mean small, repeatable actions that fit your family.
Habits are the bridge between “we talk about money” and “money feels normal.”
Examples:
- saving a small portion of gifts
- making a simple plan before a store trip
- pausing before a purchase and naming the tradeoff
A habit does not have to be perfect. It has to be repeatable.
What Financial Literacy Is Not
It helps to name what we are not doing, so you do not accidentally build pressure into something that is meant to build confidence.
Financial literacy for kids is not:
- turning kids into “mini adults”
- making them worry about adult bills
- teaching them to chase returns
- shaming them for wanting things
- expecting them to “be good at money” early
If you take one thing from this post, let it be this.
Kids do not need early sophistication. They need early familiarity.
What To Focus On At Different Ages
There is no one right timeline. But there are a few age-appropriate focus areas that tend to work well.
If Your Child Is Between 4 And 7 Years Old
At this age, the goal is simple: make money words feel normal.
Try:
- Naming what is happening out loud: “We are saving for later.” “We are choosing one today.”
- Letting them pay sometimes (with guidance), so money feels like a tool, not a mystery.
- Using clear boundaries without apology: “That is not in our plan today.”
A helpful script:
- “We can want something and still wait.”
If Your Child Is Between 8 And 12 Years Old
This is a great age for simple systems.
Try:
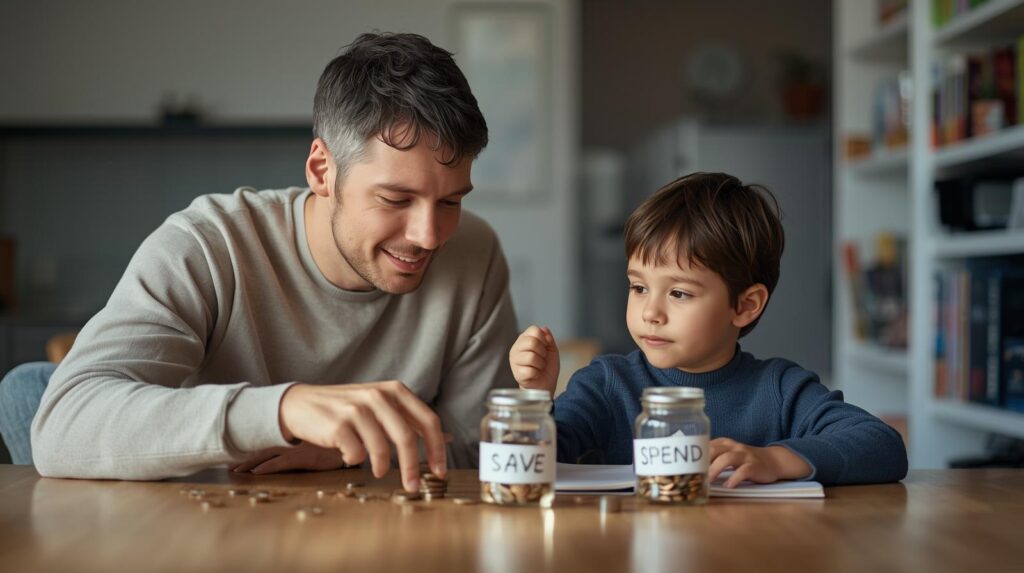
- A basic “save, spend, give” split (or “save and spend” if you want to keep it simpler).
- A short planning moment before online shopping: “What are we buying, why, and what are we not buying?”
- Talking about tradeoffs calmly: “If we spend on this, we have less for that.”
A helpful script:
- “Let’s make a plan before we decide.”
If Your Child Is Between 13 And 18 Years Old
Teens can handle more complexity, but they still do not need pressure.
Try:
- Talking about paychecks, taxes, and budgeting as a life skill, not a morality test.
- Helping them set one meaningful goal (phone, car, trip) and letting them practice planning.
- Introducing the idea of ownership in a simple way, without making it intense.
A helpful script:
- “You do not have to be perfect. You just need a system you can repeat.”
A Simple Way To Start This Week
If this still feels like a lot, start smaller than you think. Consistency beats intensity.
Here are three low-pressure starting points. Pick the one that fits your life right now.
Option 1: Add One Sentence To Real Moments
Pick one sentence and use it for a week.
Examples:
- “What is our plan for this?”
- “Is this a want or a need today?”
- “Do we want this now, or later?”
Option 2: Choose One Habit That Does Not Require More Time
A good habit is one you can do on your busiest week.
Examples:
- Save a small amount from gifts before spending.
- Do a 10-second plan before a store trip.
- Put one recurring bill on autopay and explain why (for older kids).
Option 3: Make One Money Topic Feel Less Tense
If money talk usually gets sharp, the habit might be emotional, not mathematical.
Try:
- Saying “we” instead of “you” when discussing plans.
- Replacing “because I said so” with “because we have a plan.”
- Naming your own feeling without dumping it on your child: “Money can feel stressful. We are learning to talk about it calmly.”
What To Read Next (If You Want A Simple Sequence)
If you want to keep building this in a calm way, here are three directions you can take next:
- Teaching Kids About Money Without Making It Their Job (our pressure-free philosophy)
- The Money Lessons Kids Learn From Everyday Life (what they see, hear, and absorb)
- Rethinking Allowances And Gifts (a few systems families can actually repeat)
Financial literacy for kids is not a checklist. It is comfort, language, and repeatable habits that fit real family life.
If you only do one thing this week, pick one sentence you can repeat calmly in real moments.
Save this and share with a friend or family member.
Comment with your questions.